An FOP in Group 3 without VAT registration pays three mandatory taxes in 2026: single tax at 5% of income, military levy at 1% of income, and the Unified Social Contribution (ЄСВ) of 1,902 UAH every month regardless of income.
Below are all the amounts, deadlines, and the formula for how much to set aside from every payment you receive from a client.
This article doesn’t replace an accountant’s advice. Check dates against the DPS tax payer calendar — weekend and holiday shifts differ every year.
Three payments: 5% + 1% + 1,902 UAH/month
Single tax for FOP Group 3: rate and calculation
5% of income, if you operate without VAT.
Income is everything that lands in your account or till. Not profit, not “minus expenses.”
You received 40,000 UAH in a month — single tax = 2,000 UAH.
Income limit for 2026: 10,091,049 UAH (1,167 minimum wages).
Military levy for FOP: how much and by when
1% of income. A separate payment, not part of the single tax.
In effect since 1 January 2025 (Law No. 4015-IX). Paid on the same schedule as the single tax.
No income — nothing to pay.
By law, the military levy for FOP Group 3 stays in place for another 3 years after martial law ends.
Unified Social Contribution for FOP Group 3 in 2026: amount and formula
A fixed amount: 1,902.34 UAH/month.
| Period | Amount |
|---|---|
| Month | 1,902.34 UAH |
| Quarter | 5,707.02 UAH |
| Year | 22,828.08 UAH |
Formula: 22% of the minimum wage (8,647 UAH in 2026, per the State Budget Law).
You pay it even if you earned nothing that month.
Who’s exempt from the Unified Social Contribution: – mobilised FOPs (automatically, for the duration of service) – old-age pensioners – FOPs with a disability – FOPs who also have a main place of employment where the employer has already paid Unified Social Contribution at least at the minimum
2026 calendar: when to pay what
Unified Social Contribution — by the 20th of the month after the quarter ends
| Quarter | Period covered | Deadline |
|---|---|---|
| Q1 | January–March | 20 April 2026 |
| Q2 | April–June | 20 July 2026 |
| Q3 | July–September | 20 October 2026 |
| Q4 | October–December | 20 January 2027 |
The amount is the same every time: 5,707.02 UAH.
Single tax + military levy
First you file the declaration (within 40 calendar days after the quarter), then you pay (within 10 calendar days after the declaration deadline).
| Quarter | Declaration by | Single tax + levy payment by |
|---|---|---|
| Q1 | 11 May 2026 | 20 May 2026 |
| Q2 | 10 August 2026 | 19 August 2026 |
| Q3 | 9 November 2026 | 19 November 2026 |
| Q4 | 9 February 2027 | 19 February 2027 |
You calculate the single tax and levy amount yourself: 6% of income for the quarter.
⚠️ Dates are calculated using the formula from the Tax Code, accounting for the 2026 weekend shifts. Before paying, check the current DPS tax payer calendar — public holidays can shift the deadline.
Penalties for late payment. Late payment of the single tax or Unified Social Contribution — a fine of 10% to 20% of the amount owed, plus a daily penalty (Art. 126.1 of the Tax Code and Art. 25 of the Law on the Unified Social Contribution). Failing to file the declaration — a 340 UAH fine, 1,020 UAH for a repeat violation within a year (Art. 120.1 of the Tax Code).
Formula: how much to set aside
From every payment you get from a client, set aside 6% right away. This covers the single tax (5%) and the military levy (1%).
Plus 1,902 UAH a month for the Unified Social Contribution — regardless of whether you earned anything.
Example
Income for the quarter: 150,000 UAH.
| Payment | Calculation | Amount |
|---|---|---|
| Single tax 5% | 150,000 × 0.05 | 7,500 UAH |
| Military levy 1% | 150,000 × 0.01 | 1,500 UAH |
| Unified Social Contribution | 1,902.34 × 3 | 5,707 UAH |
| Total for the quarter | 14,707 UAH |
Left in hand: 135,293 UAH. Tax burden: ~9.8% of turnover.
The smaller your income, the higher the Unified Social Contribution’s share, because it’s fixed. At an income of 30,000 UAH/quarter, the burden climbs to ~25%. If your income is consistently below 50,000 UAH/month, it’s worth calculating whether Group 2 — with its fixed rate of up to 20% of the minimum wage — would be more advantageous.
The declaration: where and how
Filed electronically through the DPS taxpayer cabinet or an accounting service.
Form: F0103309 — single tax payer’s declaration for FOPs. The Unified Social Contribution calculation is filed as Appendix 1 within the annual declaration (F0133109); a separate Unified Social Contribution report isn’t needed.
Deadline: 40 calendar days after the reporting quarter ends. Exact dates are in the table above.
Checklist: save this and check off
Here’s what this checklist looks like in my own account
I’m the one building Pivona, so this section is biased. The screenshot below only proves one thing — that a screen like this exists — and nothing about whether it calculates better than your accountant does.
I don’t calculate this by hand anymore, and I don’t keep it in a calendar. Pivona has my FOP group set, and from there the tracker calculates tax from what’s actually landed in my FOP account, not turnover from a bank statement, and reminds me 5 and 3 days before the deadline — in the dashboard and in the morning Telegram digest, if the bot is connected. The notification shows how many days overdue a payment is, while the Finances card shows just a marker and a date. You set the rates and payment terms yourself in settings, and the tracker doesn’t know about holiday shifts, so you still need to check the date against the DPS calendar.
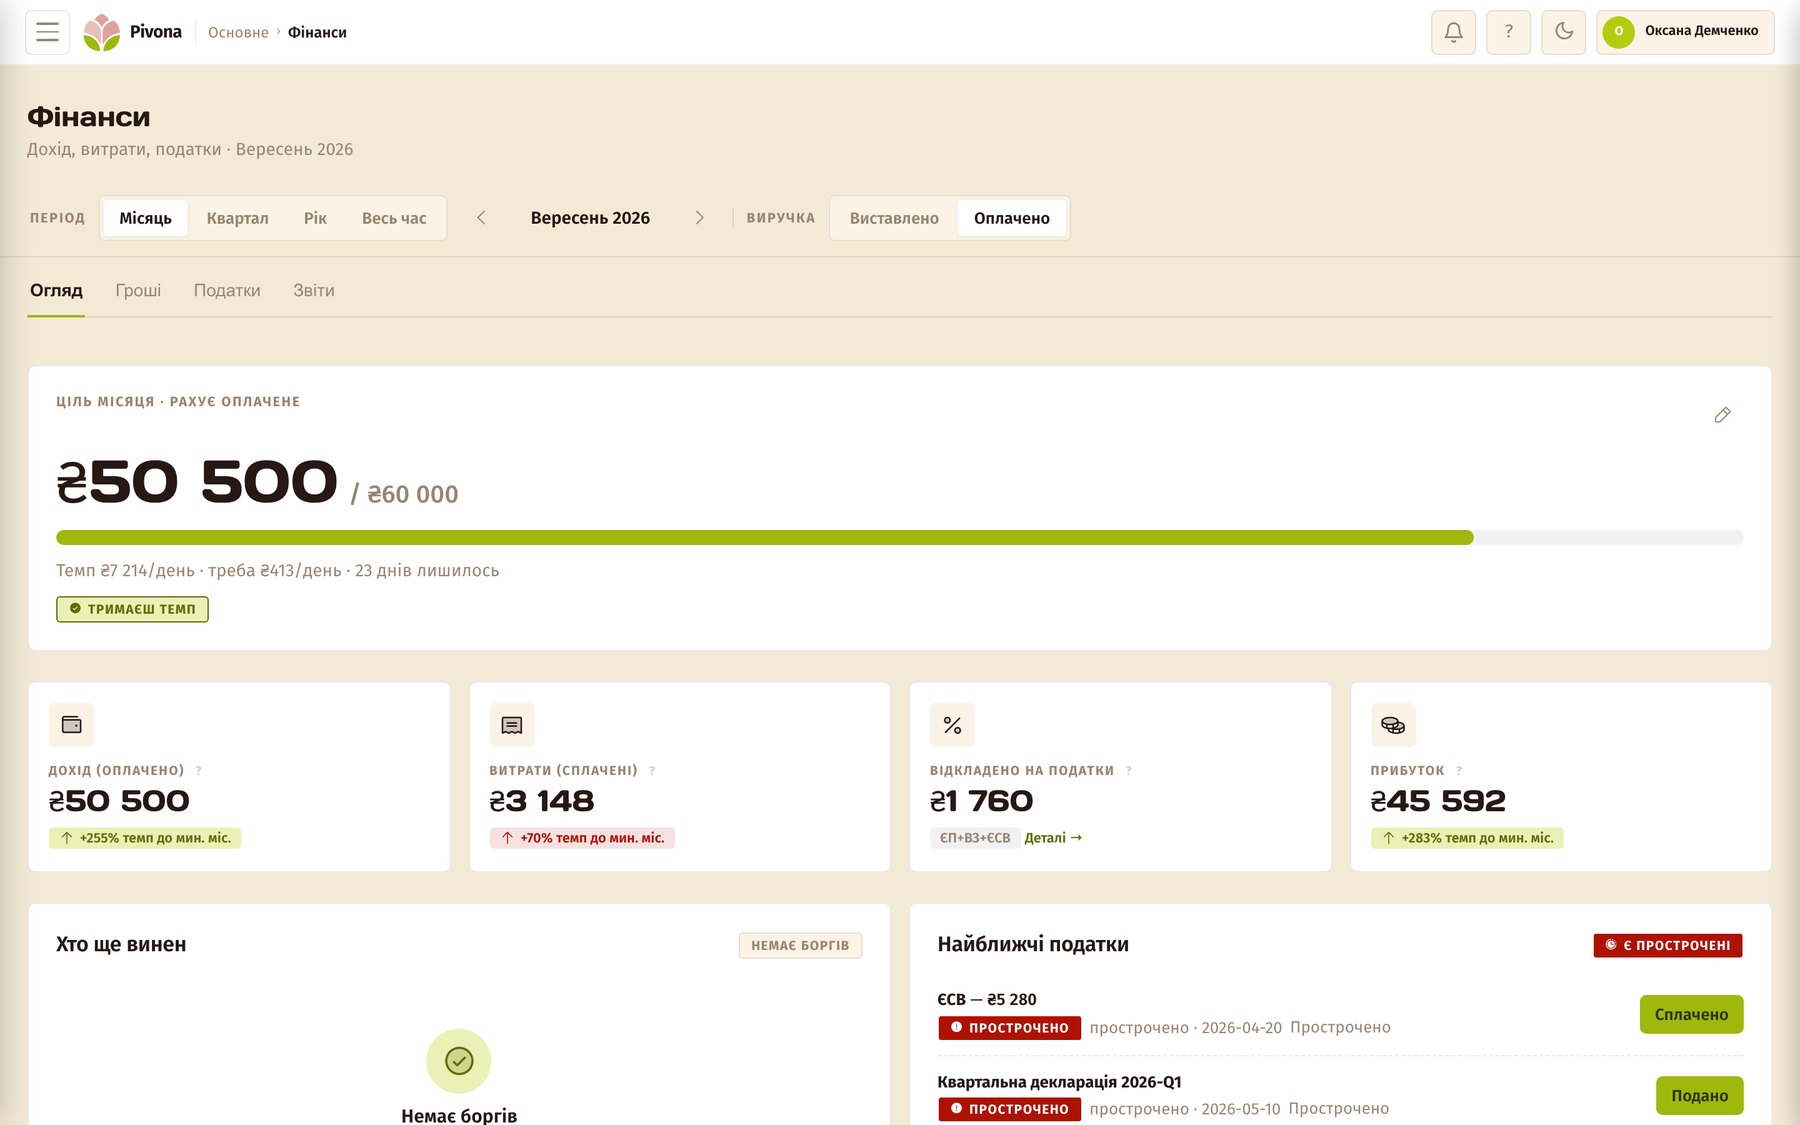
I no longer keep the date and amount in my head — that’s exactly why the tracker exists. Filing and responsibility still stay on you.
If a bookkeeper or a calendar already keeps your deadlines and it works, you can skip this section. Otherwise, the first 30 days are free, no card required: pivona.io/pro-pivona. After that it’s 1,290 UAH a month, or a free tier that keeps three active clients.
Rates and amounts are per the Tax Code of Ukraine, the DPS, minimum wage for 2026 — 8,647 UAH (Law of Ukraine “On the State Budget of Ukraine for 2026”). Penalties — Art. 120.1, 126.1 of the Tax Code, Art. 25 of the Law on the Unified Social Contribution. Updated 20 August 2026. This is not tax advice — consult an accountant for your specific situation.